

Budget App — PocketGuard
4.5

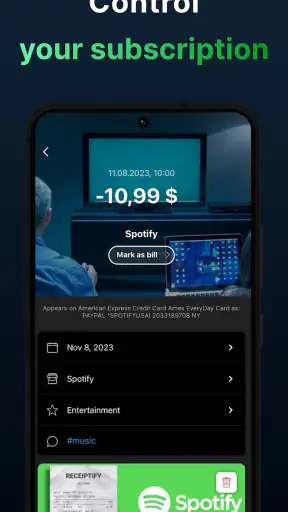
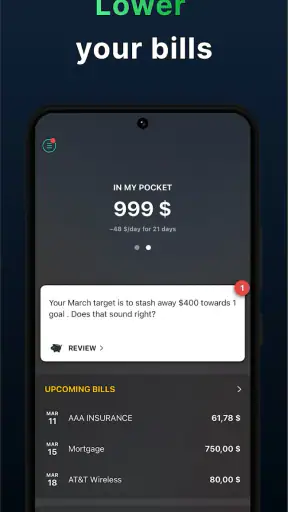
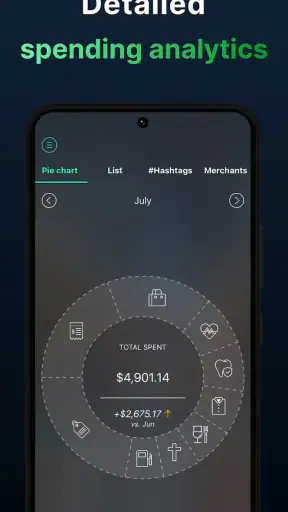
Managing money usually fails for a simple reason: the information is scattered. A bank balance shows what is available now, a card statement shows what already happened, and a spreadsheet asks you to keep updating it. PocketGuard, a finance app from PocketGuard, Inc., tries to bring those pieces into one budgeting routine so I can see spending, income, expenses, and saving decisions without building the system myself.
I approached it as a practical decision rather than a search for the most powerful money tool. The important question is not whether an app can display transactions. It is whether it helps me answer a useful everyday question: after the bills and planned spending are covered, what can I safely use? That focus makes this app appealing for people who want direction quickly, although it also means users who enjoy detailed manual planning may want something more flexible.
How I Judge PocketGuard as a Budgeting Tool
My first test for a budgeting app is clarity. I want to understand my financial position without opening several accounts and doing mental arithmetic. The second is maintenance. A system that looks impressive on the first day but takes constant effort is unlikely to survive a busy month. The third is control: I need enough detail to spot waste, recurring commitments, and timing problems before they become surprises.
PocketGuard fits best when the goal is spending awareness rather than elaborate financial modeling. Its store summary presents it as a tool for tracking spending, managing income, controlling expenses, and saving money, and that description matches the way I would use it. I would open it before making a discretionary purchase, after payday, and during a short weekly review. Those moments are more valuable than endlessly categorizing old transactions.
The app is free to download and is suitable for Everyone, which lowers the barrier for someone who wants to try a budgeting habit without committing immediately. It includes in-app purchases ranging from under a dollar to well into the triple digits per item, so I would still inspect the purchase screen carefully before treating the free entry point as the complete long-term experience. The right value judgment depends on whether its guided view saves enough time to justify any paid options that matter to you.
Its Android history also suggests that this is an established product rather than a brand-new experiment. It was released in mid-March of 2016, has passed a hundred thousand installs, and carries an average rating of four and a half from roughly three thousand ratings. Those figures do not prove that it will fit every financial situation, but they give me more confidence than an app with no visible usage history. The current version is 5.19.3 and it requires Android 8.0 or later.
The first setup matters more than the first glance
A budgeting app becomes useful only after the picture is reasonably complete. I would begin by adding the income sources and regular obligations that shape my month, then check whether the resulting view feels realistic. The temptation is to rush through setup and trust the first number displayed. I would resist that. If a bill, subscription, or irregular expense is missing, the apparent spending room can be misleading.
My practical approach would be to start with a single month that I know well. I would compare the app’s picture with recent bank and card activity, look for repeated charges, and correct obvious classification problems before making decisions. This is not busywork. It separates a useful budget from a polished but inaccurate dashboard. Once the baseline is trustworthy, later reviews become much faster.
That workflow is one of the less obvious strengths of a focused budgeting app: it can turn a vague wish to “spend less” into a repeatable check. I would not try to solve every financial goal on the first day. I would first make the everyday spending view dependable, then use it to identify one or two changes, such as reducing impulse purchases or setting aside money immediately after income arrives.
A realistic payday and grocery scenario
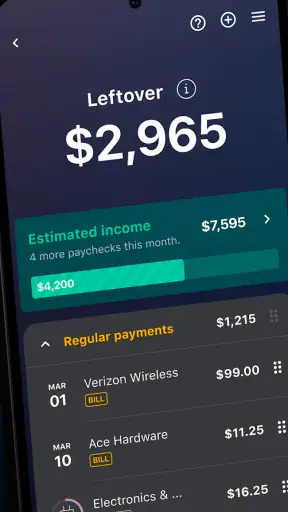
Imagine I am paid on a Friday. The balance looks comfortable, but rent, utilities, a card payment, and a grocery trip are all approaching. Without a planning view, I might treat the visible balance as permission to order dinner, replace headphones, and accept a weekend invitation. PocketGuard is more useful when I check the amount left after the known commitments rather than reacting to the headline balance.
In that situation, I would review the planned obligations first, then examine recent spending in categories that tend to drift. Groceries are a good example because several small visits can become a large monthly total without feeling dramatic at the time. If the app makes the remaining room easier to understand, I can decide whether the headphones fit this pay cycle or should wait. The benefit is not a lecture about frugality; it is a clearer connection between today’s purchase and the rest of the month.
I would repeat the check after the grocery trip, not just at payday. That second look catches the common mistake of budgeting once and then forgetting that real spending changes the picture. A short review also helps distinguish a genuine problem from a one-off event. A large purchase for a birthday should not automatically become a permanent reason to slash an ordinary category.
Where the app earns its place
The strongest case for PocketGuard is the person who wants a quick answer without maintaining a custom spreadsheet. It can be a good match for someone starting a first budget, a household that wants a shared view of ordinary spending, or a user who repeatedly reaches the end of the month wondering where the money went. The app’s emphasis on income, expenses, and available spending makes it easier to act on information instead of merely collecting it.
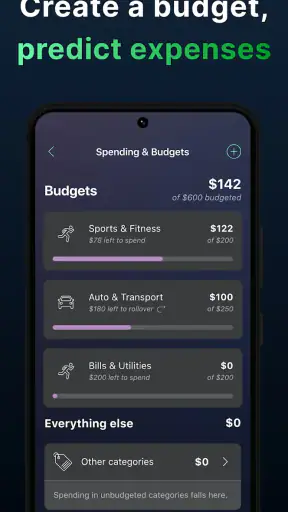
I also see value for people who dislike traditional envelope-style budgeting. Some systems require assigning every unit of money to a category before spending. That can be powerful, but it may feel restrictive or tedious. PocketGuard’s more direct orientation toward what remains after commitments can be easier to understand when the main problem is overspending between paydays.
Another useful habit is to treat the app as a conversation starter for couples or families. Rather than arguing over whether someone “spends too much,” I would look together at recurring obligations, recent categories, and the amount available for flexible use. That shifts the discussion from blame to choices. It does not replace agreement about priorities, but it gives the conversation a common reference point.
For saving, I would use the app as a guardrail rather than a complete financial plan. Once I know what is genuinely free after necessities, I can move a chosen amount toward a goal or savings account. The important trade-off is timing: saving only whatever happens to remain at the end of the month is less reliable than deciding on a transfer early. PocketGuard can help reveal the room for that decision, but the discipline still belongs to me.
Small routines that make the view more trustworthy
I would schedule a short weekly review instead of constantly checking the app. During that review, I would look for unusual charges, recurring expenses that have quietly increased, and categories that are consistently underestimated. This prevents the tool from becoming another source of notification anxiety while preserving its main advantage: timely awareness.
I would also separate fixed commitments from flexible choices in my thinking. A monthly bill is not the same as a restaurant visit, even if both appear in the same overall spending picture. When I see a disappointing total, I want to know which part can actually change. That distinction makes the app more useful because it turns a large number into a practical next step.
A third tactic is to review the budget before a known high-spending week. Travel, school events, holidays, and annual renewals can distort an ordinary month. I would check those periods in advance and reduce optional spending temporarily rather than pretending the unusual costs will not happen. This is a more realistic use of a budgeting app than expecting every month to look identical.
Finally, I would avoid changing too many categories at once. If I cut dining, entertainment, shopping, and transport simultaneously, I may not know what actually helped. I prefer choosing one visible target, watching it for a few weeks, and then deciding whether the change is sustainable. The app can show the pattern, but a manageable experiment produces better information than an extreme reset.
Where another kind of money app may fit better
PocketGuard is not automatically the best choice for everyone. A spreadsheet may be better for a user who wants complete control over formulas, custom categories, forecasts, or unusual income. Manual tools take more work, but that effort can be worthwhile when the budget is complex or when privacy preferences make account aggregation unattractive.
A zero-based budgeting service may suit someone who wants every incoming amount assigned before it is spent. That approach is especially useful for irregular income, debt payoff plans, or households that need firm limits for each category. PocketGuard’s quick “what can I use?” orientation may feel too broad if I need strict permission for every purchase.
Banking apps can be enough for a person who only needs balances and recent transactions. They are convenient because the information is already tied to the financial institution, but they often do not provide the same budgeting focus. I would choose the bank’s own tool when simplicity and direct access matter more than a dedicated spending overview.
On the other hand, people with investments, taxes, multiple businesses, or detailed net-worth goals may outgrow a consumer budgeting app. Their needs involve reporting and planning beyond ordinary expense control. PocketGuard makes more sense as a personal spending companion than as a complete financial command center.
The friction of changing from another system
Switching tools is not free, even when the download costs nothing. The real cost is rebuilding trust in the new view. I would not delete a spreadsheet or abandon an existing budgeting method on the first day. For one pay cycle, I would compare both systems, check whether recurring obligations appear correctly, and note any difference in how spending is grouped.
This parallel period is particularly important for households. Two people can describe the same expense differently, and a category that seems obvious to one person may not match the other’s habits. Agreeing on a small set of practical rules is more useful than chasing perfect labels. For example, decide whether delivery fees belong with dining or transport, then apply that choice consistently.
I would also consider the emotional cost of a tool that exposes uncomfortable spending. A clear number can be motivating, but it can also encourage avoidance if every opening feels like a reprimand. My solution would be to use PocketGuard at specific decision points and focus on one action after each review. A budget should make choices easier, not turn every purchase into a moral judgment.
The purchase model deserves attention during that transition. Since the app is free with in-app purchases, I would try the basic experience first and identify which part of the workflow I actually use. I would not pay simply because a premium option exists. I would pay only if it removes a recurring obstacle, saves meaningful time, or supports a budgeting habit I am already maintaining.
Who should install it, and who should skip it
I would recommend PocketGuard to someone who wants a friendly starting point for personal finance tracking, especially when the main concern is spending too freely after bills are accounted for. It is also a sensible choice for a user who has tried spreadsheets and stopped updating them, because reducing manual effort can be more valuable than adding advanced controls.
I would be more cautious for anyone with highly irregular income, complicated shared finances, or a strong need to manually define every rule. Those users should compare the app’s guided approach with a more customizable budget before moving everything over. Someone who refuses any paid upgrades should also examine the free experience closely and decide whether it provides enough value without optional purchases.
People using older Android hardware should check compatibility before planning a switch, since the app requires Android 8.0 or later. For supported devices, the age rating of Everyone makes it approachable for a broad audience, but suitability is still about financial needs rather than age alone. A teenager learning basic spending awareness and a self-employed adult managing variable cash flow need very different levels of control.
My recommendation after weighing the trade-offs
My overall view is positive, with a clear boundary. PocketGuard is most convincing when I need a simple, current picture of spending room and a low-maintenance way to notice where money is going. It is less convincing as the sole tool for detailed forecasting, complex household rules, or intensive financial planning.
The app’s established presence, free starting point, and accessible purpose make it easy to test without turning the decision into a major commitment. I would install it, build a careful baseline, and use it through at least one normal pay cycle before judging it. The key test would be whether I make better decisions because the app is open at the right moment—not whether I can admire a neatly organized dashboard.
My recommendation is to try PocketGuard if your biggest budgeting problem is uncertainty about what you can safely spend. Give it a fair setup, verify the first picture against your real obligations, and keep the weekly review short. If you need every dollar assigned, extensive customization, or business-level financial detail, choose a more specialized alternative instead. For everyday expense awareness and a clearer path from income to spending and saving, this finance app is a practical option worth considering.
4.5
1.16K Reviews
Pros
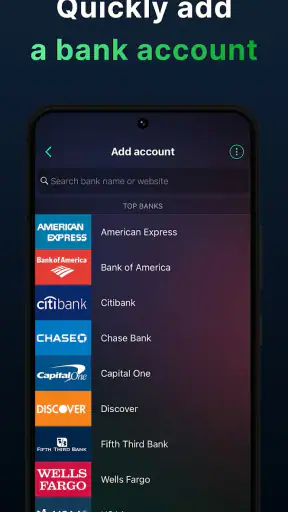
- Connects bank accounts to provide an overview of spending and available funds.
- Automatic categorization makes recurring spending patterns easier to identify.
- Useful bill and subscription tracking helps reduce forgotten monthly charges.
- Simple interface is approachable for users new to budgeting apps.
- Supports savings goals to encourage more intentional money management.
Cons
- Many useful features require a paid PocketGuard Plus subscription.
- Bank connection availability and reliability can vary by country and institution.
- Automatic categories may occasionally need manual corrections.
- Some users may dislike sharing financial data with a third-party service.
- Limited customization may frustrate people wanting a highly detailed budget system.


